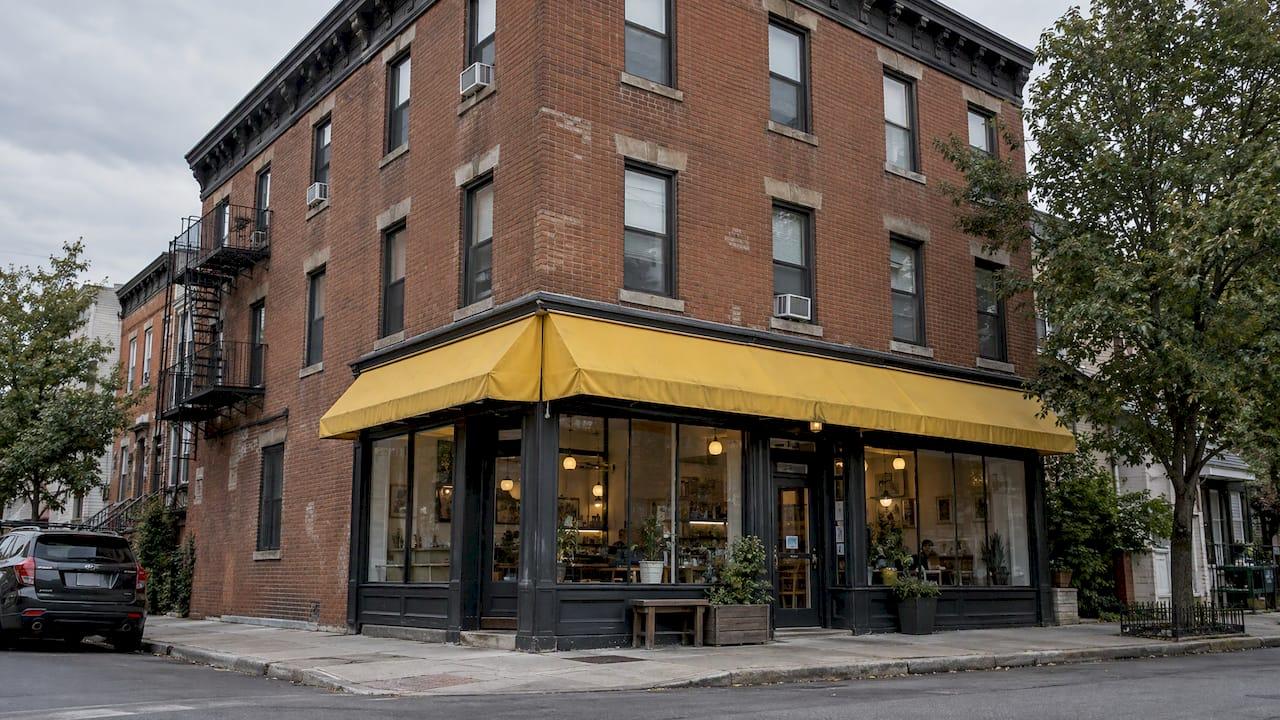
A mixed-use bridge loan is short-term, asset-based financing for a building that combines commercial space (retail, office, restaurant) with residential units. Investors and developers use it to acquire, renovate, reposition or refinance a property when a conventional lender cannot move fast enough or will not underwrite the property in its current condition. The loan is repaid by a sale or by refinancing into permanent debt. Jaken Finance Group offers mixed-use property bridge loans for retail-plus-residential assets nationwide.
TL;DR
- A mixed-use bridge loan finances buildings with both residential and commercial space for a short term, with repayment through a sale or refinance.
- Underwriting focuses on the property: value, income potential, the business plan and the exit, rather than the borrower's credit score alone.
- Jaken's published rate range for bridge loans is 8.99-13.5%, with leverage up to 100% LTC and closings in as few as 7-10 days, as our own program terms state.
- The residential-to-commercial split changes how a property is classified and underwritten, so confirm it before you apply.
- Plan at least two exits before closing: a primary refinance or sale, and a backup.
Table of Contents
- What a mixed-use bridge loan is
- Why classification matters for mixed-use property
- When investors use a mixed-use bridge loan
- Rates, leverage and terms
- Qualifying: what lenders review
- What affects closing speed
- Repayment and exit strategies
- Bridge loan or another structure?
- Local mixed-use markets
- Our perspective
- Start a mixed-use bridge loan request
- FAQ
- Sources
What a mixed-use bridge loan is
A bridge loan covers the gap between a property's current state and the state at which long-term financing becomes available. In a mixed-use building, that gap often has several causes at once: vacant storefronts, apartments needing renovation, a change in tenant mix, or a seller who needs a fast close.
Typical collateral includes:
- Apartments above ground-floor retail
- Live-work buildings and small office-over-residential properties
- Buildings with restaurants or service tenants below and units above
- Larger multifamily properties with a commercial component
The loan is secured by the real estate. The lender evaluates what the property is worth today, what it will be worth after the work, and how the borrower plans to leave the loan. This is what makes bridge financing different from a bank's permanent mortgage, which usually requires stabilized occupancy and a documented operating history.
Why classification matters for mixed-use property

Lenders do not treat every mixed-use building the same way. According to HSH.com, a mixed-use property may be classified as commercial or residential depending on the proportions of each use. A typical configuration of many apartments over a few stores is handled as an apartment loan, while a 50-50 split or a building with more commercial space triggers a more conservative underwriting structure.
For a bridge borrower, the practical consequences are:
- Leverage: a commercial-heavy building is usually underwritten more conservatively than a residential-heavy one.
- Exit financing: the permanent loan you plan to refinance into depends on the same classification, so the right takeout product differs by property.
- Valuation method: residential-heavy buildings lean on rent comparables, while commercial space is valued on lease terms, tenant quality and income.
Before you request a quote, put together the square footage by use, current rent roll, lease expirations for commercial tenants, and the planned post-renovation mix. That package lets the lender classify the asset and price it accurately the first time.
When investors use a mixed-use bridge loan
Acquiring a property that does not qualify for permanent debt
Many mixed-use buildings are bought with vacancies, deferred maintenance or below-market leases. A permanent lender wants stabilized income. A bridge loan lets you close, fix the issues and then refinance.
Closing on a tight timeline
Auction purchases, estate sales and motivated sellers often require closing in days. Asset-based underwriting shortens the process because the lender is focused on the property and the plan. Jaken's program is built for closings in as few as 7-10 days.
Funding renovation and repositioning
Common scopes include unit renovations, storefront improvements, code and safety upgrades, and converting underused commercial space to residential or the reverse. Our article on commercial rehab bridge loans for value-add projects covers how rehab budgets are structured.
Buying out of a maturing loan
When an existing loan is about to mature and the borrower cannot refinance on the lender's terms, a bridge loan can pay off the debt and provide time to complete a lease-up or renovation.
Bridging to a sale
Some investors buy, stabilize and sell instead of refinancing. A bridge loan supports that strategy when the hold period is short and the resale value depends on completing the work.
Rates, leverage and terms
Terms vary by lender, property, market and borrower. These are Jaken's published and stated program parameters:
| Item | Jaken Finance Group |
|---|---|
| Bridge loan rate range | 8.99-13.5% |
| Commercial property loan rate range | 8.99-13.5% |
| Maximum leverage | Up to 100% LTC |
| Closing speed | As few as 7-10 days |
| Minimum credit score | None |
| Payment structure | Deferred payment options available |
| Coverage | Nationwide |
A few points of terminology help when comparing quotes:
- LTV (loan-to-value): the loan divided by the property's appraised value.
- LTC (loan-to-cost): the loan divided by purchase price plus renovation budget. High-LTC programs fund a larger share of the total project cost.
- ARV (after-repair value): the projected value once the work is complete, which many lenders use to cap the loan on renovation deals.
- Origination points: the upfront fee, usually quoted as a percentage of the loan amount.
- Balloon payoff: the full principal due at maturity, which is how most interest-only bridge loans are repaid.
Compare quotes on total cost, not only the rate. Add origination points, closing costs, rehab draw fees and any extension fees, then calculate the cost over your realistic hold period, not the stated term.
Qualifying: what lenders review
Asset-based lending shifts the emphasis from the borrower's financial statements to the deal. Expect to provide:
- Purchase contract or current payoff statement for the property
- Property details: address, square footage by use, unit count and current occupancy
- Rent roll and leases for existing residential and commercial tenants
- Renovation scope and budget, if the loan includes rehab funds
- Exit plan: whether you will refinance or sell, and the timeline
- Entity documents if you are borrowing through an LLC
- Experience summary, which supports your capacity to execute the plan
Because Jaken has no minimum credit score requirement, investors with varied credit profiles can still pursue a mixed-use acquisition when the property and plan support the loan.
What affects closing speed
A fast close depends as much on file readiness as on the lender. These items most often set the timeline:
- Appraisal or valuation: mixed-use properties can require appraisers familiar with both residential and commercial valuation.
- Title and survey: older mixed-use buildings may have easements, liens or zoning issues that take time to clear.
- Insurance: a policy covering both uses must be in place before closing.
- Tenant documentation: estoppels and leases for commercial tenants add steps that a single-family loan does not have.
- Entity paperwork: a complete operating agreement and good standing certificate avoid delays.
Sending a complete package at the start is the most reliable way to reach the 7-10 day range.
Repayment and exit strategies
A bridge loan is only as sound as its exit. The main risk is time: renovation delays, slow lease-up or a change in refinance conditions can leave the property unready when the loan matures. Build the plan around that risk.
Primary exit: refinance into permanent debt
Once the building is renovated and leased, you can refinance into a long-term loan. For residential-heavy mixed-use buildings, rental-income-based products such as DSCR loans can qualify the property on its cash flow. Our DSCR calculator shows whether projected rent covers the debt service on a planned takeout loan. DSCR rental loans from Jaken are listed at 5.75-10.5%, and you can review the full lineup on our loan options page.
Secondary exit: sale
If values or rates move against a refinance, a sale can repay the bridge loan. Estimate the net proceeds after costs at a conservative value and confirm they exceed the payoff.
Other options
An equity partner, subordinate financing or a refinance with a portfolio lender can also take out a bridge loan. Our gap lending and portfolio refinance products serve borrowers who need to close a funding shortfall or consolidate holdings.
Risk checklist before you close
- Does the renovation schedule have a buffer of several months beyond the base case?
- Does the refinance still work if appraised value is lower than projected?
- Do you have an extension option and its cost in writing?
- Is there a second exit that does not rely on the first?
Bridge loan or another structure?
A bridge loan is not the only way to finance a mixed-use deal. The right structure depends on condition and plan.
| Situation | Usually fits |
|---|---|
| Stabilized, fully leased, long hold | Permanent commercial or residential mortgage |
| Vacant or under-leased, value-add plan | Bridge loan |
| Heavy renovation of a small building | Rehab-focused bridge or fix-and-flip structure |
| Ground-up building with retail and units | New construction loan |
| Cash-out on a leased rental | DSCR cash-out or portfolio refinance |
If the plan is a quick renovation and resale, see how fix-and-flip loans compare with bridge loans. For buildings with five or more residential units, our multifamily bridge loan page covers that segment, and ground-up projects are handled under new construction loans for investors.
Local mixed-use markets
Mixed-use inventory is concentrated in dense urban corridors, and local rules affect each deal. Zoning, ground-floor use restrictions and permitting timelines vary by city. We maintain local pages for Chicago mixed-use bridge loans, Illinois mixed-use bridge loans and Washington, DC mixed-use bridge loans. Investors in other states, including Florida and Indiana, can also finance through our nationwide program.
Our perspective
Mixed-use buildings are hard for conventional lenders because the income comes from two asset classes and the property often needs work before it looks like a bank loan. That is where asset-based bridge financing fits. We underwrite the building, the business plan and the exit, which is why we do not set a minimum credit score.
In our experience, deals stall for three reasons: unclear classification, an incomplete rent roll and no backup exit. We built our program for investors who solve those three items up front. Leverage up to 100% LTC, deferred payment options and closings in as few as 7-10 days are designed to keep a project moving while the value-add work is completed.
Our advice is to define the takeout loan before you close the bridge loan. If you know whether the building will refinance as a residential rental, a commercial asset or a sale, you can set the renovation budget and timeline to match.
Jason Taken
Start a mixed-use bridge loan request
Jaken Finance Group provides bridge, fix-and-flip, new construction, DSCR rental, gap and commercial property loans to real estate investors across the United States. For a retail-plus-residential building, send the address, square footage by use, rent roll, renovation budget and your exit plan. Need financing for your next project? Review our bridge loan options for real estate investors and request terms.

For larger or commercial-weighted assets, see commercial property loans by asset class. For a broader introduction, read what to know about bridge loans.
FAQ
What is the difference between a mixed-use bridge loan and a regular commercial bridge loan?
The structure is the same: short-term, interest-only financing repaid by a sale or refinance. The difference is the collateral. A mixed-use building has residential and commercial income, so classification, valuation and the takeout loan all depend on the split between uses.
How long does a mixed-use bridge loan last?
Bridge loans are short-term by design, and the exact term is set in the loan agreement based on the business plan. Choose a term that covers your renovation and lease-up schedule with a buffer, and confirm extension terms in writing before closing.
Can I get a mixed-use bridge loan with a low credit score?
With asset-based lending, the property and plan carry the most weight. Jaken Finance Group has no minimum credit score requirement. Provide a complete deal package so the property value and exit can be assessed quickly.
How fast can a mixed-use bridge loan close?
Our program is built for closings in as few as 7-10 days. The speed depends on a complete file, a timely valuation, clear title and proof of insurance. Commercial tenant documents can add steps, so gather leases early.
What happens if I cannot refinance when the loan matures?
That is why a second exit matters. Options include selling the property, bringing in an equity partner, or refinancing with a different lender type. Talk to your lender about extension terms well before maturity rather than at the deadline.