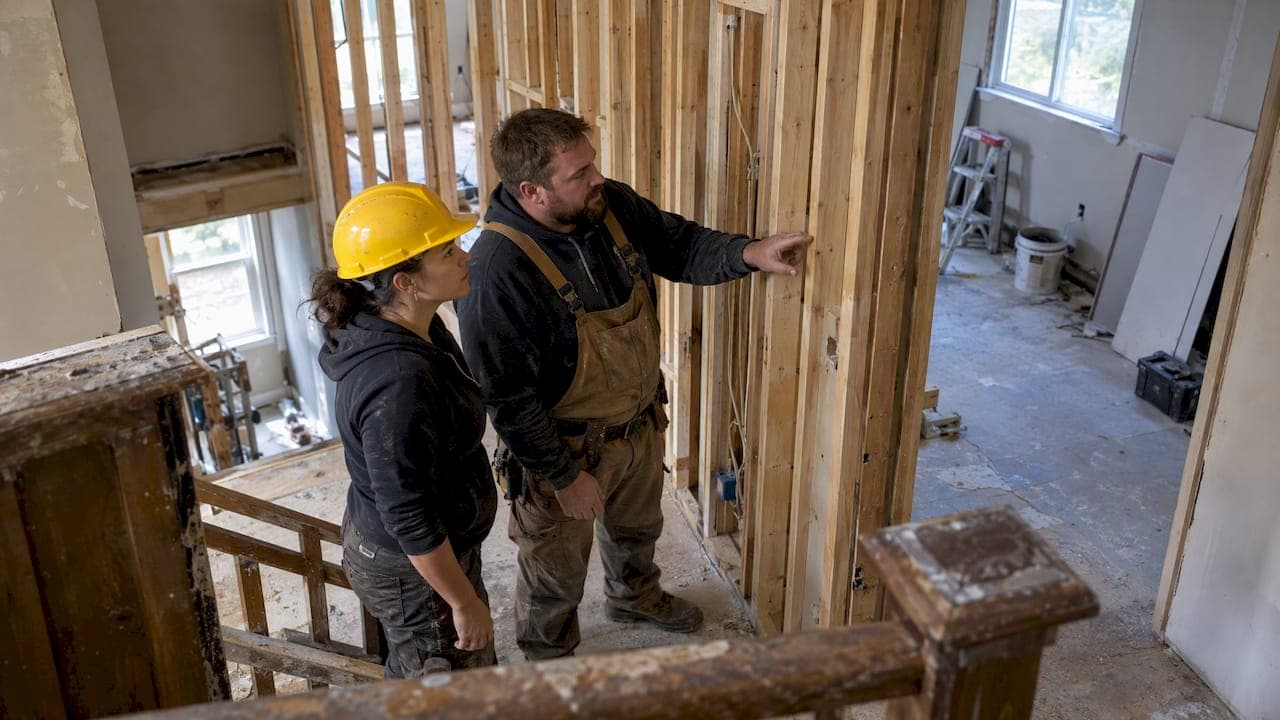
A fix-and-flip credit line is a short-term, asset-backed borrowing facility that funds purchase and staged rehab costs, and investors choose it for speed and flexible draws rather than low headline rates. It suits a reader who needs capital released in stages as renovation work completes, not a single lump-sum loan. Most lines are repaid at sale or refinance within six to twenty-four months.
TL;DR:
- A credit line releases rehab funds by completed milestones, usually after invoice review and inspection; lenders may retain 10% until completion and lien releases.
- A $250,000 purchase and $75,000 rehab example estimates about $26,000 in financing costs over six months, including points and interest.
- Lenders prioritize after repair value, contractor credibility, and a clear exit over income records; prepare work costs, contractor bids, comparable sales, and proof of funds.
- Plan a sale or refinance within six to twelve months, and budget one to two extra months of carrying costs for delays.
- Flips sold within a year are usually taxed as ordinary business income, but entity and activity classifications vary, so confirm treatment with a tax professional.
Table of Contents
- 1. What a fix-and-flip credit line covers and how draws work
- 2. Types of credit lines: single-property, portfolio, and business lines
- 3. Typical terms, costs, and a worked example
- 4. Qualification and underwriting: what lenders evaluate
- 5. Draw schedules, inspections, and lender controls on disbursements
- 6. When a fix-and-flip credit line is the right structure
- 7. How Jaken Finance Group structures fix-and-flip credit lines
- 8. Moving from a fix-and-flip credit line to permanent financing or sale
- 9. Tax implications and deductions tied to a fix-and-flip credit line
- 10. Common pitfalls with fix-and-flip credit lines
- 11. A lender's view on exit planning and documentation
- Get a fix-and-flip credit line that matches your deal timeline
- FAQ
- Sources
1. What a fix-and-flip credit line covers and how draws work
A fix-and-flip credit line funds the acquisition and the renovation budget tied to that acquisition, released in pieces as work progresses rather than all at once. Eligible costs typically include:
- Property acquisition or purchase price
- Demolition and site preparation
- Contractor labor and material invoices
- Permit fees and inspection costs
- Holding costs such as insurance and property taxes during rehab
- Interest reserves set aside to cover monthly payments
- Contingency reserves for unexpected scope changes
Draw requests follow a documented process. We submit a draw request tied to a completed phase, supported by contractor invoices and, in most programs, a site inspection confirming the work matches the request. Regulatory guidance on construction lending recommends exactly this structure: staged draws tied to invoices, inspections, and lien releases before funds move, which protects both the lender's collateral position and the investor's project budget, according to the Comptroller's Handbook on construction lending. The flow runs from an approved credit limit at closing, through sequential draws as milestones complete, to a final payoff at sale or refinance.
2. Types of credit lines: single-property, portfolio, and business lines
Investors can choose from a few structural variations, each suited to a different volume of activity and underwriting posture.
- Single-property lines: tied to one deal, sized to that property's purchase price and rehab budget, and closed out when the property sells or refinances.
- Portfolio or blanket lines: cover multiple properties under one facility, suited to repeat operators who want to avoid re-underwriting every deal; renewal terms and reporting requirements tend to be stricter.
- Business or stated-income lines: underwritten against the investor's business entity rather than a single asset, often with lighter income documentation but higher pricing or lower limits as a trade-off.
A first-time flipper working one property at a time generally fits a single-property line. An operator running several rehabs at once benefits more from a portfolio structure, since it reduces closing friction across deals even though it demands stronger ongoing underwriting and reporting.
3. Typical terms, costs, and a worked example
Rate alone rarely tells the full story. Total carry cost, which combines interest, points, and holding expenses over the actual hold period, is what determines whether a flip stays profitable. Hard money and fix-and-flip financing typically prices in a range from the high single digits to the mid-teens annually, plus a few origination points, according to Herring Bank's lending overview. Loan sizing commonly caps at a portion of after-repair value, or ARV, which is the projected resale price once renovations are complete.
A typical hard money structure closes in 5 to 15 business days, far faster than conventional mortgage underwriting, which lets investors move on time-sensitive acquisitions (Herring Bank).
Here is a worked example based on figures from that same source: a $250,000 purchase plus $75,000 in rehab costs, financed at 70% of ARV, at an 11% annual rate with 3 points.
| Line item | Amount |
|---|---|
| Purchase price | $250,000 |
| Rehab budget | $75,000 |
| Total project cost | $250,000 |
| Origination points (3% of $250,000) | $7,500 |
| Interest over a 6-month hold at 11% | approximately $16,250 |
| Estimated total financing cost | approximately $26,000 |
Term structures are typically interest-only during the draw period, with the full balance due at payoff when the property sells or the investor refinances into permanent financing.
4. Qualification and underwriting: what lenders evaluate
Fix-and-flip underwriting is asset-first. Lenders weigh the property's after-repair value, the loan-to-value and loan-to-cost ratios, the credibility of the contractor doing the work, and the clarity of the exit plan more heavily than a borrower's income documentation. The Comptroller's Handbook on commercial real estate lending recommends that construction and renovation underwriting include realistic cost estimates and a clearly identified source of repayment, a standard that shapes how most asset-based lenders structure their own review.
To prepare a fast application, gather:
- A detailed scope of work with line-item costs
- Contractor bids or a signed construction contract
- Recent comparable sales supporting the projected ARV
- Proof of funds for any purchase gap not covered by the line
- A clear exit statement: sale, refinance, or rental hold
Credit score plays a limited role in many asset-based programs compared to conventional mortgages, since the property's value and the investor's exit plan carry more underwriting weight than a FICO number.
Pro Tip: Order your comparable sales and contractor bids before applying so the lender can verify ARV and scope in the same review cycle instead of two.
5. Draw schedules, inspections, and lender controls on disbursements
Lenders attach operational controls to every draw to make sure funds match completed work, not projected work. Regulatory guidance on construction lending points to inspections, segregation of duties on disbursements, and holdbacks until completion as standard practice, documentation that protects the lender's collateral and keeps the investor's budget honest (OCC Examination Handbook 213).
- Draws are typically tied to percentage-of-completion milestones rather than a fixed calendar.
- An inspection usually triggers before funds release, confirming the invoiced work is physically in place.
- A holdback or retainage, often 10% of each draw, is withheld until final completion and lien releases are filed.
- Lien waivers from contractors and subcontractors are standard documentation before the final draw clears.
Coordinating contractor payment schedules with the lender's draw calendar in advance avoids cash-flow gaps that stall a project mid-renovation.
6. When a fix-and-flip credit line is the right structure
A fix-and-flip credit line fits deals where speed and staged funding matter more than the lowest possible rate.
- Speed to close, often inside two weeks rather than the 30 to 45 days typical of conventional financing
- Staged rehab funding that matches cash outlay to work completed instead of borrowing the full budget upfront
- Reusable capacity across multiple deals when structured as a portfolio line
The trade-off is higher carrying cost than a bank loan, plus the draw documentation and inspection requirements covered above, so contingency reserves and realistic margins matter more than on a conventional purchase. A quick fit check: does the project have a clear six-to-twelve-month exit, a predictable rehab scope, and enough margin to absorb one or two unexpected draw delays? If yes, a credit line is likely the right tool.
7. How Jaken Finance Group structures fix-and-flip credit lines
Closings can happen in as few as 7 to 10 days, which matters most on competitive acquisitions where a slow lender loses the deal.
- We require a scope of work, contractor information, and comparable sales up front, matching the documentation standards covered earlier in this guide.
- Draws follow the same inspection and invoice-backed structure that regulatory guidance recommends for construction lending.
- Our fix-and-flip loan rates page lists current program pricing by deal type.
- Our fix-and-flip calculator lets you model financing cost against projected profit before you apply.
Investors structuring a deal with a credit partner can review our breakdown of fix-and-flip financing with a credit partner in an LLC for partnership and entity considerations.
8. Moving from a fix-and-flip credit line to permanent financing or sale
A fix-and-flip credit line is built to be temporary, so every project needs a defined exit before the first draw closes. The two common paths are sale and refinance.
Selling at or near the projected ARV pays off the balance directly, and the gap between the original loan amount and the net sale proceeds becomes realized profit once financing costs and selling expenses are subtracted. This is the cleanest exit and the one most credit lines are underwritten to expect, usually within six to twelve months of closing.
Refinancing into permanent financing applies when the plan shifts from flip to hold. An investor who decides to keep a property as a rental typically refinances the short-term balance into a longer-term loan, such as a DSCR rental loan sized against the property's rental income rather than the investor's personal income. That refinance pays off the credit line in full and converts the position into long-term, amortizing debt.

The timing of either exit matters as much as the exit itself. Because most fix-and-flip structures carry interest-only payments and a defined draw period, a delayed sale or a refinance that takes longer than expected extends the carry cost calculated earlier in this guide. Building a buffer of one to two months beyond the projected timeline into the budget protects margin if a buyer's financing stalls or a refinance appraisal comes in lower than the renovation plan assumed. Investors weighing financing structures broadly can review our overview of fix-and-flip financing strategies for additional context on when each exit path makes sense.
9. Tax implications and deductions tied to a fix-and-flip credit line
Interest paid on a fix-and-flip credit line is generally treated as a business expense tied to the project rather than a personal mortgage interest deduction, since the property is held as inventory for resale rather than as a personal residence or long-term rental. Origination points and certain closing costs typically follow the same treatment, added to the project's cost basis or deducted as financing expenses depending on how the investor's accountant structures the transaction.
Profit from a flip sold within a year of acquisition is usually taxed as ordinary income rather than at long-term capital gains rates, because the IRS generally views active flipping as a trade or business rather than a passive investment. That distinction affects both the tax rate applied and whether self-employment tax considerations come into play for an individual investor flipping properties as a primary activity.
Because tax treatment depends on entity structure, holding period, and how the IRS classifies the activity for a given investor, a certified tax professional should confirm the specific deductions and classification that apply before a return is filed. The mechanics described here are general and not a substitute for that review.

10. Common pitfalls with fix-and-flip credit lines
The most frequent mistake is underestimating total carry cost. A headline rate looks manageable until points, interest over an extended hold, and holding costs stack up, which is why the worked example earlier in this guide matters more than the rate alone.
- Underestimating hold time. Every extra month on a stalled sale or a slow permit adds a full interest cycle to the carry cost.
- Treating the draw schedule as a formality. Inspections and invoice documentation take real time to assemble; building that lag into the contractor payment calendar avoids mid-project cash gaps.
- Skipping contingency reserves. Renovation scope changes are common, and a credit line without a contingency buffer can leave a project short mid-rehab.
- Ignoring exit certainty. A flip without a realistic comparable-sales basis for ARV, or a refinance plan without a lender lined up, turns a short-term facility into an open-ended liability.
None of these pitfalls are unique to one lender or program; they are structural features of short-term, draw-based financing, and planning around them is what separates a profitable flip from a break-even one.
11. A lender's view on exit planning and documentation
Model your exit and your carry cost before you model your profit margin, because a flip that works on paper at a projected six-month hold can lose money at nine months if the financing cost was never stress-tested. Run your numbers through a fix-and-flip calculator before bidding, not after.
— Jason Taken
Get a fix-and-flip credit line that matches your deal timeline
Fix-and-flip credit lines are often structured around the deal, use asset-based underwriting, have no minimum credit score requirement, and can close in as few as 7 to 10 days when the file is complete.
Review current pricing on our fix-and-flip loan rates page, then run your purchase and rehab numbers through our fix-and-flip calculator before you commit, so your carry cost is accounted for from day one.
FAQ
What credit score do you need for a fix and flip loan?
Many fix-and-flip lenders underwrite primarily against the property's value and the investor's exit plan, so credit score requirements vary widely by program and some require no minimum at all. Asset-based programs weigh after-repair value and contractor credibility more heavily than a FICO number.
How to get a 700 credit score in 30 days fast?
There is no reliable or verified way to raise a credit score by a fixed amount in 30 days, since scoring models weigh payment history and credit utilization over longer reporting cycles. Paying down revolving balances and correcting any reporting errors are the two levers most likely to move a score within a short window, but results vary by starting profile.
Is it hard to get a fix and flip loan?
Approval difficulty depends more on the strength of the deal than the borrower's financial profile, since asset-based lenders weigh ARV, scope of work, and exit plan heavily. A well-documented project with solid comparable sales and a credible contractor typically moves through underwriting faster than one lacking that documentation.
Is fix and flip risky?
Fix-and-flip investing carries real execution risk, since renovation overruns, slower-than-planned sales, and financing costs that stack up over an extended hold can all compress or erase profit margin. Modeling worst-case timelines and carrying costs before committing, as shown in the worked example above, is the primary way investors manage that risk (Forbes Advisor).
Sources
- Hard Money Loans: How They Work and When to Use Them | Herring Bank
- What Is A Hard Money Loan? | Forbes Advisor
- Examination Handbook 213, Construction Lending, January 1994